Romanian
 English

REPORT ON ALTERNATIVE DISPUTE RESOLUTION AS AT 30.09.2026
During the first nine months of 2026, as many as 793 consumers went through the entire conciliation process: application filing, negotiation, final resolution => a solution accepted by both parties in 460 cases, or reached an amicable settlement directly with their banks/NBFIs, after having first approached ABDRC (in 333 cases).
During the first nine months of the year, 73 court cases were dropped because the parties wanted and managed to find an amicable solution in ABDRC (compared to 89 lawsuits dropped in the same period of 2025).
The number of applications recorded in the first nine months of the year (3,394 applications) shows a visible increase compared to the similar period of 2025 (2,121 applications), i.e., up approximately 60% YoY. Some consumers continued to experience genuine difficulties in making the due payments, and these justified circumstances required identification of solutions to rebalance the contractual obligations (with the applications being submitted directly to creditors, or via ABDRC).
Of the total number of applications received before the end of Q3 2026, 2,287 applications addressed different issues in relation with banks (1,620 in Q3 2025), whereas 1.107 applications concerned different issues in relation with NBFIs (501 in Q3 2025).
Thus, the share of applications intended at NBFIs slightly increase above last year’s reference period: from 23.6% of total/at the end of Q3 2025, to 32.6% of total/at the end of Q3 2026.
Moreover, the share of applications intended at banks observes a slight decrease in the two periods subject to comparison: 76.4% of total/at the end of Q3 2025, and 67.4% of total/at the end of Q3 2026.
During the first the nine months of this year, the number of applications for deregistration from the Credit Bureau (CB) observed a slight increase YoY; however, their share has dropped out of total (when applied to this year’s reporting base (60% higher than the same reference period of last year). At the end of Q3 2026, we see 513 applications for deregistration from the CR (337 intended at banks + 176 intended at NBFIs), while the number of this type of applications recorded at the end of Q3 2025 was 500 (282 intended at banks + 218 intended at NBFIs). It should be recalled that most of the applications aimed at deregistration from the Credit Bureau are closed because there is a special law in place for these cases, and this prevents such negotiations.
The total number of cases formed by the end of Q3 2026 reached 572, all of which concerned banks. By way of comparison, 686 case were formed in the first nine months of 2025. Of the case formed this year and settled until the end of the reference period, 460 concluded with a resolution (the parties accepted the solution proposed by the conciliator), while other 48 cases are still being processed (at the end of Q3 2026). In 54 cases, one of the parties rejected the solution proposed by the conciliator and a report was issued, whereas in 10 cases, one of the parties withdrew from the procedure.
The number of resolutions handed down in the first nine months of this year is 460, compared to the figure reported for the same period of last year, i.e., 595 resolutions (during the two periods under review, being by the end of Q3 2026 and by the end of Q3 2025, the share of resolutions out of the total solutions is 96%/at the end of Q3 2026, and 90% of total resolutions/at the end of Q3 2025, respectively).
Furthermore, by the end of the Q3 2026, 333 applications were settled amicably by traders after the respective cases having been referred to ABDRC (traders negotiated directly with consumers), broken down as follows: 277 applications settled amicably with banks, and 56 applications settled amicably with NBFIs (v the end of Q3 2025: 217 applications settled directly, of which 176 by banks and 41 by NBFIs). In fact, compared with the same period last year, the number of applications settled amicably by banks is 150% higher.
At the end of Q3 of this year, we counted 2,216 enquiries made by phone, and 499 persons/consumers accessed the chat function available on the ABDRC website (v at the end of Q3 2025, when we recorded 1,318 phone enquiries, and 293 persons accessed the chat on the ABDRC website).
A breakdown of the applications by traders looks as follows:
Banks:
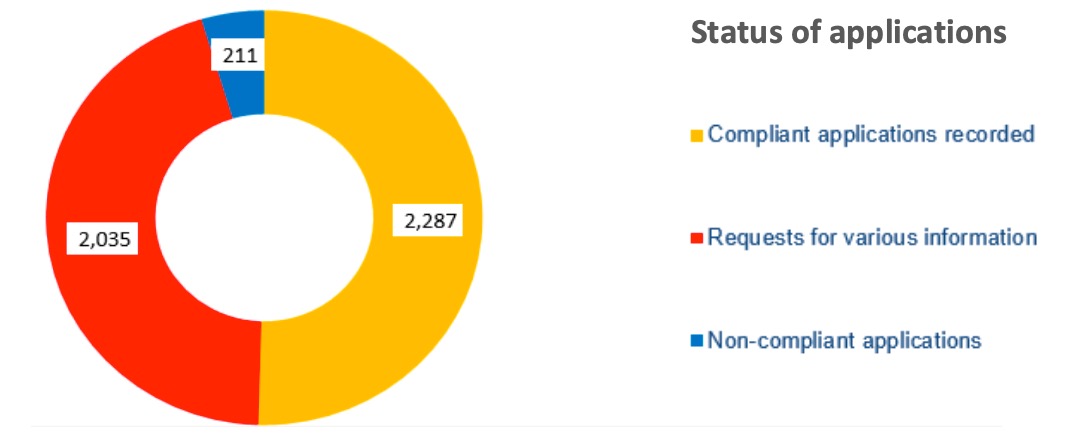
- 2,287 compliant applications;
- 211 non-compliant applications;
- 2,035 requests for miscellaneous information.
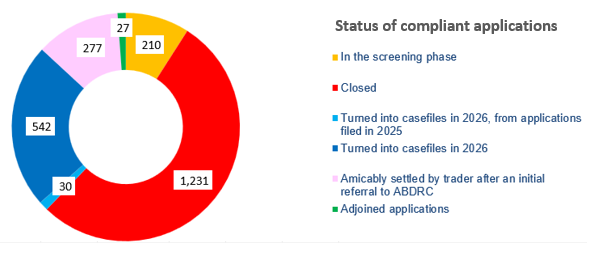
Classification of the 2,287 compliant applications:
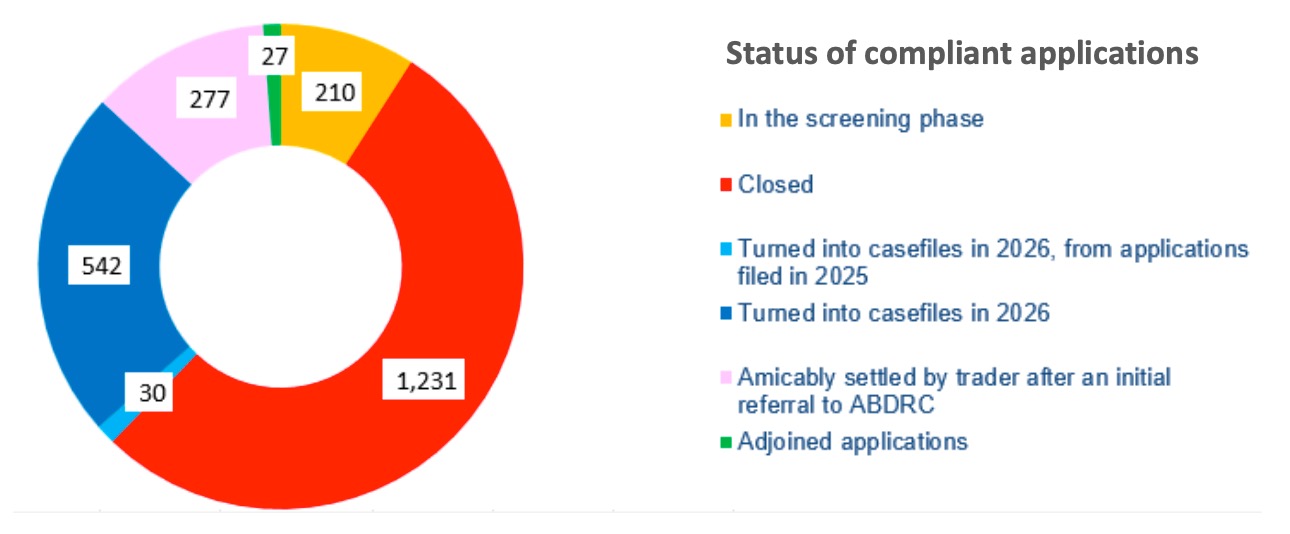
- 572 cases formed in the end of Q3 2026 (at the start of 2026, 30 cases were formed from compliant applications received in late 2025);
- 210 applications in screening phase – documents are being reviewed;
- 277 applications were settled amicably by the parties, after the consumer having first referred their grievances to ABDRC;
- 1,231 cases were closed;
- 27 applications were adjoined.
Classification of the 572 case undergoing the procedure with proposed solution/conciliation:
- 460 resolutions were handed down – the parties came to terms;
- 48 cases are in the processing phase;
- 54 reports – the parties did not come to terms;
- 10 cases in which one of the parties withdrew.
Methods of filing compliant applications – regardless of the referral channel, all compliant applications are entered into the IT application used to manage applications and casefiles:
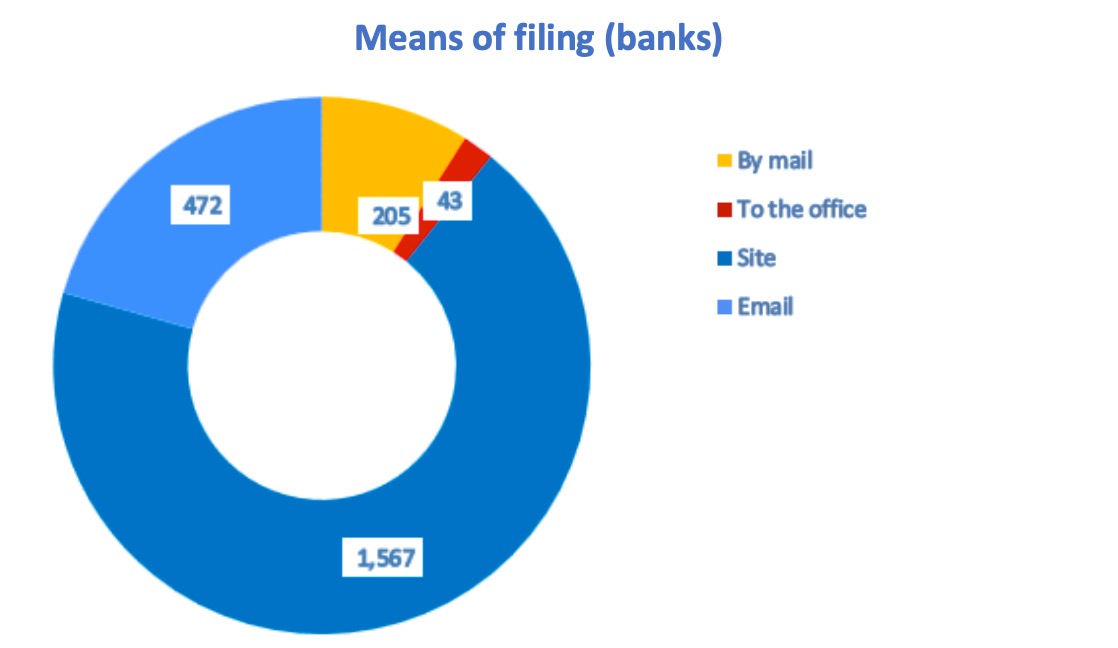
- 1,567 were submitted via the app (website);
- 472 were filed by email;
- 205 were mailed;
- 43 were brought to, and registered by consumers in person, with the office of ABDRC.
NBFIs:
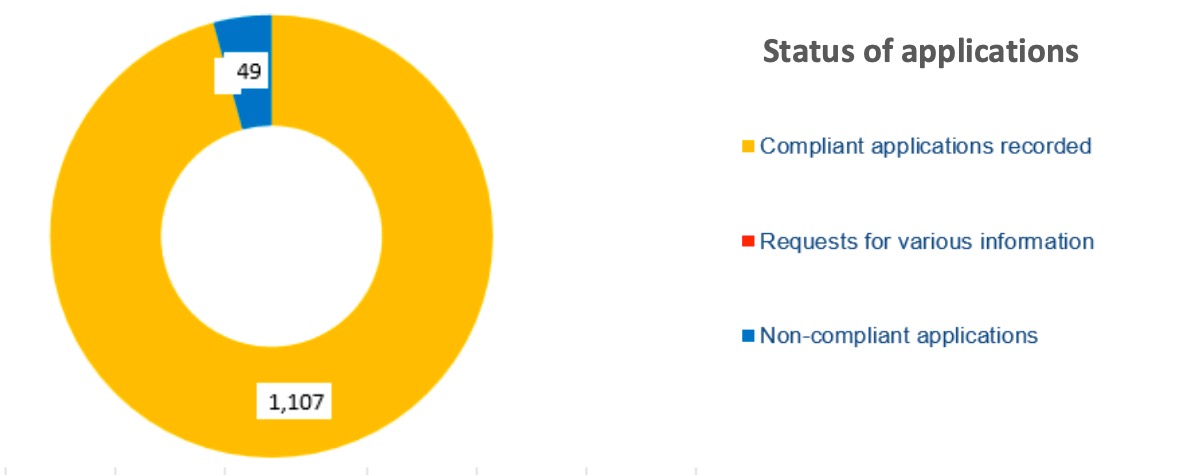
- 1,107 compliant applications;
- 49 non-compliant applications.
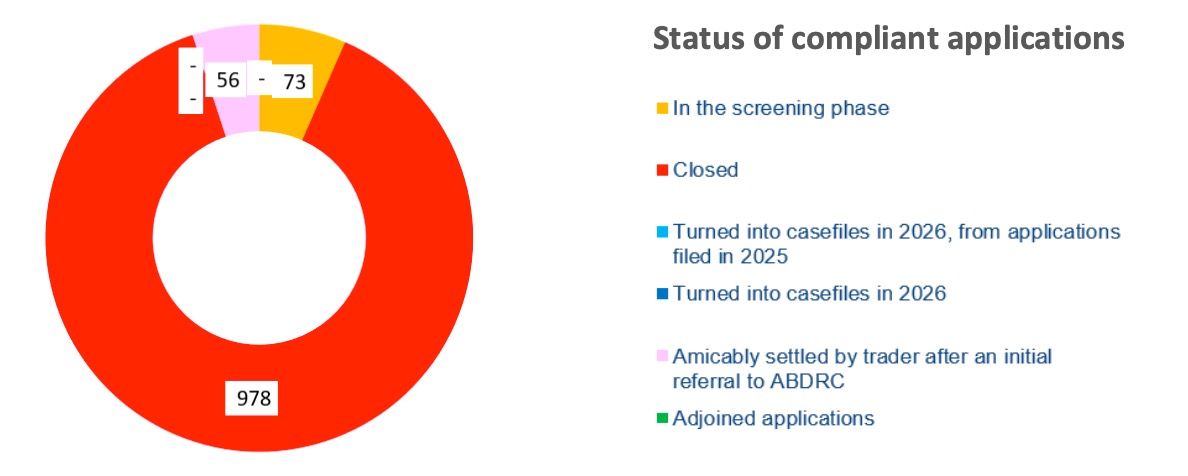
Classification of the 1,107 compliant applications:
- 73 applications in the screening phase;
- 56 applications were settled amicably between NBFIs and consumers, after the consumer having first approached ABDRC;
- 978 were closed – rejected by the NBFIs.
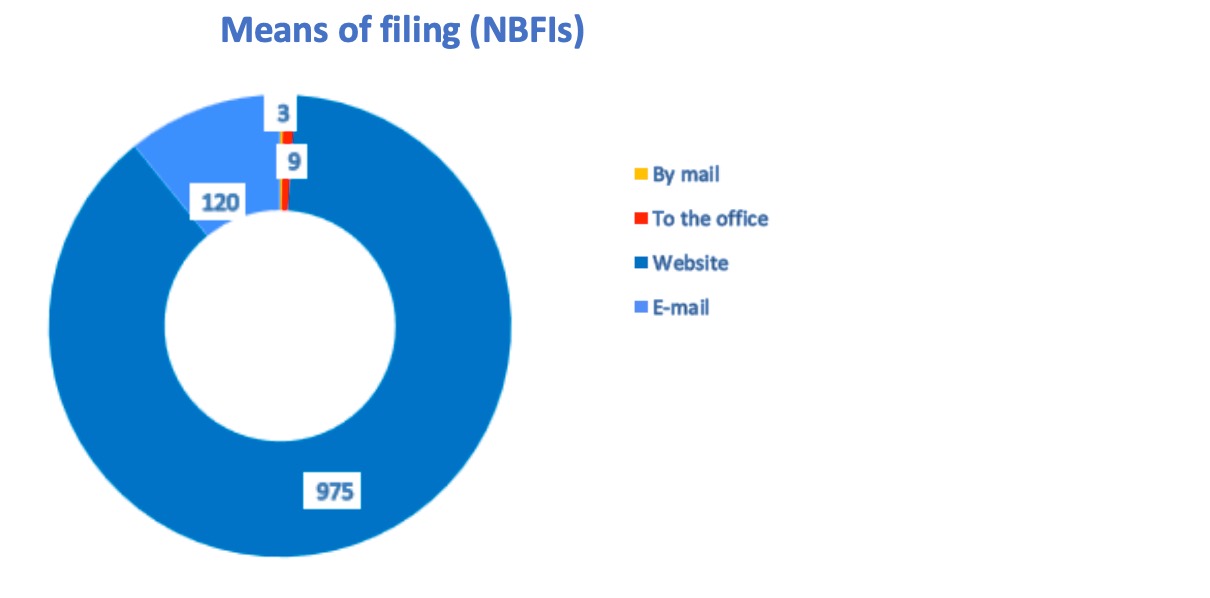
Means of filing compliant applications:
- 975 were submitted via the app (website);
- 120 were filed by email;
- 9 were brought to, and registered by consumers in person, with the office of ABDRC;
- 3 were mailed.
The applications received from consumers covered the following topics:
- Problems in connection with credit products:
-
- Refunds (of fees/commissions, interest);
- Reduction of loan principal/debt/instalment, or writing off overdue amounts;
- Rescheduling/refinancing/staging-out;
- Agreement renegotiation/rebalancing (including for hardship);
- Finding a solution to address the problems (in general);
- Shift from ROBOR to IRCC;
- Conversion of the loan currency;
- Problems with insurance policies (bancassurance);
- Interest recalculation;
- Payment commitments;
- Maturity acceleration;
- Removal of certain clauses;
- Credit Bureau (deregistration from CB).
- Operational problems:
-
- Problems with operation of the ATMs (including refunds);
- Problems in connection with wire transfers and refunds of transaction fees;
- Refunds in case of processing errors;
- Recovery of amount wrongly transferred by consumers (internet banking);
- Provision of clarifications about calculation of the amounts withdrawn by banks from the credit card account;
- Other card-related problems (cancellation/name change);
- Problems in connection with the exchange rate and interests charged when using the cards abroad;
- Problems regarding inter-banking transfers.
- Problems related to other types of activities:
-
- Problems in connection with forced execution (suspensions/stays of proceedings);
- Requests to be issued documents (repayment schedules, statements of account, mortgage deregistration, etc.);
- Refunds of garnished amounts;
- Fraud committed via bank channels.
The main reason for closing an application is the refusal of traders to have the dispute settle via ADR procedure, and the reasons for closing fall into several categories:
- Good reasons (main) – the application concerns:
- deregistration of entries from the Credit Bureau;
- “First Home” loans;
- claim assigned to companies which are not regulated by the National Bank of Romania;
- the state premium under saving-credit contracts.
- Reasons related to consumers:
- selection of a trader the business of which is not regulated by the National Bank of Romania;
- selection of a trader they don’t have commercial relations with;
- the information/documents required for resolving the application have not been supplied;
- the consumer does not reply within 90 days, or withdraws during negotiations.
- Other reasons:
- pending court proceedings;
- forced execution procedures have already been initiated;
- while traders made several offers, all of them were turned down by consumers (before referring the matter to ABDRC), and traders maintain their point of view in the initial answer;
- lack of grounds (claimed by the trader).
BENCHMARKING:
| Q3 2025 in figures:
· 2,121 compliant applications – 236 applications per month; · 595 cases concluded with resolutions/the parties coming to terms (an average of 66 resolutions/month), of 686 cases formed at the end of Q3 2025 (an average of 76 cases/month); · 217 applications settled amicably by the parties after an initial referral to ABDRC – (an average of 24 amicably settled applications & applications settled directly between the parties per month).
2025 in figures (entire year): · 2,866 applications – 239 applications per month; · 911 cases – 76 cases per month; · 336 applications settled amicably – 28 amicably settled applications/month. |
Q3 2026 in figures:
· 3,394 compliant applications – 377 applications per month; · 460 casefiles concluded with resolutions/the parties coming to terms (an average of 51 resolutions/month), of 572 casefiles formed at the end of Q3 2026 (an average of 64 casefiles/month); · 333 applications settled amicably by the parties after an initial referral to ABDRC – (an average of 37 amicably settled applications & applications settled directly between the parties per month). |
CONCLUSIONS:
The ABDRC services continue to be accessed by the Romanians who have problems with banks/NBFIs. Benefits of conciliation: the court proceedings are avoided and the contractual relations between parties continue; short case settlement time (an average of approximately half of a month over the last years, namely 14 days/2024 and 13 days/2025); the fact that the procedure is free of charge for consumers, added to the expertise of conciliators, are all important benefits for both consumers and the financial and banking institutions involved in these negotiations, particularly during economically difficult times, not only at national, but also at international level.
In this context, the conclusions drawn for the first nine months of 2026 are as follows:
- During the first nine months of 2026, Romanians filed 3,394 applications for negotiation with banks and NBFIs (i.e., 60% more than in the same period of 2025).
- The share of applications intended at banks (out of total) went down from 76,4% to 67,4%, although banks received more applications at the end Q3 2026 than at the end of Q3 2025. The applications intended at NBFIs went up by 220% in the first 9 months of 2026, as compared to the same period of 2025 (from 501 at the end of Q3 2025, up to 1,107 at the end of Q3 2026); their share out of the total applications increased from 23,6% (at the end of Q3 2025) to 32,6% (at the end of Q3 2026). However, NBFIs did not accept any applications for negotiation via ABDRC, and direct settlements (between NBFIs and consumers, without the involvement of a conciliator) occurred in 56 cases. Thus, only 5% of the total 1,107 applications intended at NBFIs found a solution.
- Negotiable applications account for 85% of the total /at the end of Q3 2026. At the end of Q3 2025, negotiable applications accounted for 76.5%; in the same period of 2024, this was 71.8%.
This is due to a drop from 803 (at the end of Q3 2024) down to 500 (at the end of Q3 2025), and to 513 (at the end of Q3 2026), in the number of applications for deregistration from the Credit Bureau (which cannot be negotiated via ABDRC, but are settled directly by the parties or are closed).
- The number of cases reached 572/at the end of Q3 2026 as compared to 686/at the end of Q3 2025. Thus, of the 1,950 negotiable applications intended at banks, 572 were turned into negotiation cases, meaning that approximately 30% of applications concerning banks were resolved with the help of an ABDRC conciliator, while 12% were settled directly between the trader and the consumer after having first approached ABDRC.
- In 460 cases, the consumers came to terms with their banks, after having accepted the solution proposed by conciliators.
- The fact that the traders operating in the financial and banking system continued to welcome the amicable (direct) settlement further to a referral to ABDRC is another way of solving the claims raised by consumers, particularly when these claims concern simple matters and do not necessarily require the intervention/expertise of the ABDRC conciliators: 333 such cases/at the end of Q3 2026 v 217 such cases at the end of Q3 2025. In this instance too, banks resorted to this (direct) resolution method more often than NBFIs (277 applications resolved directly by banks, compared to 176 at the end of Q3 2025, and 56 by NBFIs, compared to 41 at the end of Q3 2025).
- ABDRC has been running annual awareness, financial education and communication campaigns involving commercial banks, journalists and ABDRC conciliators. Over the recent years, more and more people are finding out about ABDRC’s existence and work from the Centre’s communication and awareness campaigns.
- ABDRC’s communication strategy for 2026 focuses on the topic of financial education, with a dedicated section on the Centre’s website, where consumers can watch more than 40 podcasts on topics related to lending, saving, investment and personal budget management. These debates have featured (over the years) presidents and vice-presidents of commercial banks, conciliators, representatives of the National Bank of Romania, of the Romanian Association of Banks and of ABDRC, as well as financial analysts and journalists.
- In January 2026, ABDRC reviewed the profile of the consumer of financial services that approached the Centre in 2024-2025. After having reviewed the 6,434 applications for negotiation with banks/NBFIs filed to ABDRC in 2024 and 2025, we see that the profile of the consumer of financial and banking services is that of a man from the urban environment, mainly from Bucharest or the central part of Transylvania, aged between 41 and 50 years, with a consumer loan in RON, who asks their bank, via an application filled out directly on the website csalb.ro, for a reduction of the costs attached to their loans in progress.
- In the first part of this year, the ABDRC representatives have continued to meet with high-school students during Săptămâna Altfel (A Different Kind of a Week), and to deliver financial education trainings tailored to their age and needs.
- The csalb.ro website has a section dedicated to financial education, where one can find narrative and video information that consumers can rely on to make their financial decisions.
- The informative productions of ABDRC are promoted both on ABDRC’s own channels (website, Facebook, LinkedIn, YouTube, Instagram, and TikTok), and via our media partners: TV and radio outlets, online media, local press, blogposts.
- Another way of informing consumers is the ABDRC newsletter sent out to consumers of financial services who subscribed to receive this information. A new page was created on the csalb.ro website to allow consumers to sign up for the ABDRC Newsletters.
- Via its call-centre, ABDRC contacts consumers who want this (having agreed to this in various social media campaigns) by phone. They receive information about an alternative procedure to settle their disputes with banks/NBFIs.
- On the csalb.ro website, consumers can chat live with the ABDRC’s call centre operators. In the first nine months of 2026, the chat was accessed by 499 persons, compared to 293 persons who accessed the chat at the end of Q3 2025. The increased need for information among the consumers of financial products and services was also seen in the higher number of people who called ABDRC’s call centre: 2,216 phone enquiries in at the end of Q3 2026, compared to 1,318 at the end of Q3 2025.
- At the end of Q3 2026, the negotiation procedures involving consumers and banks and facilitated by ABDRC, resulted into benefits of close to EUR 1.18 million (this year). Thus, the total amount of the benefits obtained (in the more than 10 years of operational activity of the Centre) is approximately EUR 18.7 million.
- During September and October 2026, working meetings were held between representatives of ABDRC, representatives of banking institutions and conciliators, with the aim of identifying solutions to streamline the operational processes. These discussions focused on rendering workflows more efficient, improving collaboration between the parties involved, and strengthening the alternative dispute resolution mechanisms for disputes between consumers and banks.
The WEBSITE www.csalb.ro makes available also for legal entities an online tool, which allows for faster and smoother submission of the conciliation applications. On the first page of the website, consumers are prompted to access this application by filling in an application. On average, it takes 7 minutes to fill out the application directly on the website csalb.ro.
The documents entered in the registration form are uploaded into the app, and their processing time is approximately one hour. The application was setup in observance of the principles of the General Data Protection Regulation (GDPR).
The Alternative Banking Dispute Resolution Centre (ABDRC) is an independent non-governmental, apolitical, and not-for-profit legal entity of public interest established under the Government Ordinance no. 38/2015 on alternative resolution of disputes between consumers and traders, which transposes at domestic level Directive 2013/11/EU on alternative dispute resolution for consumer disputes and amending Regulation (EC) no. 2006/2004 and Directive 2009/22/EC.